Buying Property on Credit in Costa Rica: What You Really Need to Know
Introduction
Dreaming of owning a home near the beach, surrounded by lush nature and a slower, sunnier lifestyle? Every year, more and more foreigners are turning that dream into reality by purchasing property in Costa Rica. Whether you’re looking for a vacation home, a rental investment, or a retirement spot, Costa Rica offers some compelling real estate opportunities. But when it comes to financing that purchase, one big question always comes up: can you buy a property on credit in Costa Rica, especially as a foreigner?
The good news? Yes, you can. The not-so-good news? It’s not always straightforward. From traditional bank mortgages to private loans, from residency requirements to money transfer regulations, there’s a lot to understand before you sign on the dotted line.
Chances are you’re asking yourself: can I get a mortgage if I’m not a resident? What kind of interest rates should I expect? Are private lenders a better option? How easy is it to transfer money into Costa Rica? Will the local banking system make things harder or easier?
In this guide, we’ll walk you through everything you need to know about buying real estate on credit in Costa Rica. Whether you’re an experienced investor or just starting to explore the idea of owning property abroad, we’ll give you clear, useful, and up-to-date information to help you make the right decisions.
We’ll break down the different types of loans, the guarantees required, how to avoid common mistakes, and the key steps to take when transferring funds internationally. If you’re serious about buying in Costa Rica, this article is your essential starting point.
Mortgage Loans in Costa Rica: What Banks Actually Offer
Let’s start with the basics: mortgage loans through local banks. In Costa Rica, several banks offer mortgages for property purchases, but the conditions can vary significantly depending on whether you’re a resident or not.
If you’re a legal resident in Costa Rica, you’ll have access to similar mortgage options as Costa Rican nationals. Major banks like BAC San José, Banco Nacional, and Banco de Costa Rica typically offer mortgage loans with interest rates ranging from 8% to 10% annually. Repayment terms can go up to 30 years, making it easier to manage monthly payments.
However, be ready for a highly documented and bureaucratic process. Banks will ask for proof of stable income, ideally from within Costa Rica, such as pay stubs or local tax returns. You’ll also need to provide local credit history, banking references, and possibly a guarantor. If you’re self-employed, you’ll need certified financial statements.
But what if you’re not a resident? Here’s where things get tricky. Most local banks do not lend to non-residents or people with no financial footprint in Costa Rica. Even if you have solid income abroad, Costa Rican banks often lack the tools or the risk appetite to assess your overseas creditworthiness.
Some international banks, like Scotiabank, may offer tailored products for foreign buyers, but expect a long and complex application process. You’ll need to submit translated, apostilled documentation and wait several weeks—or even months—for approval.
Due to these challenges, many foreign buyers turn to private lenders, which we’ll discuss next. But if you’re already living and earning in Costa Rica, a traditional bank mortgage might be the most cost-effective option—just be prepared for paperwork and patience.
Private Loans: Flexible but Expensive Alternatives
When local banks say no, private loans can be your saving grace. And for many foreign buyers in Costa Rica, they’re the most realistic option. But like all shortcuts, they come with trade-offs.
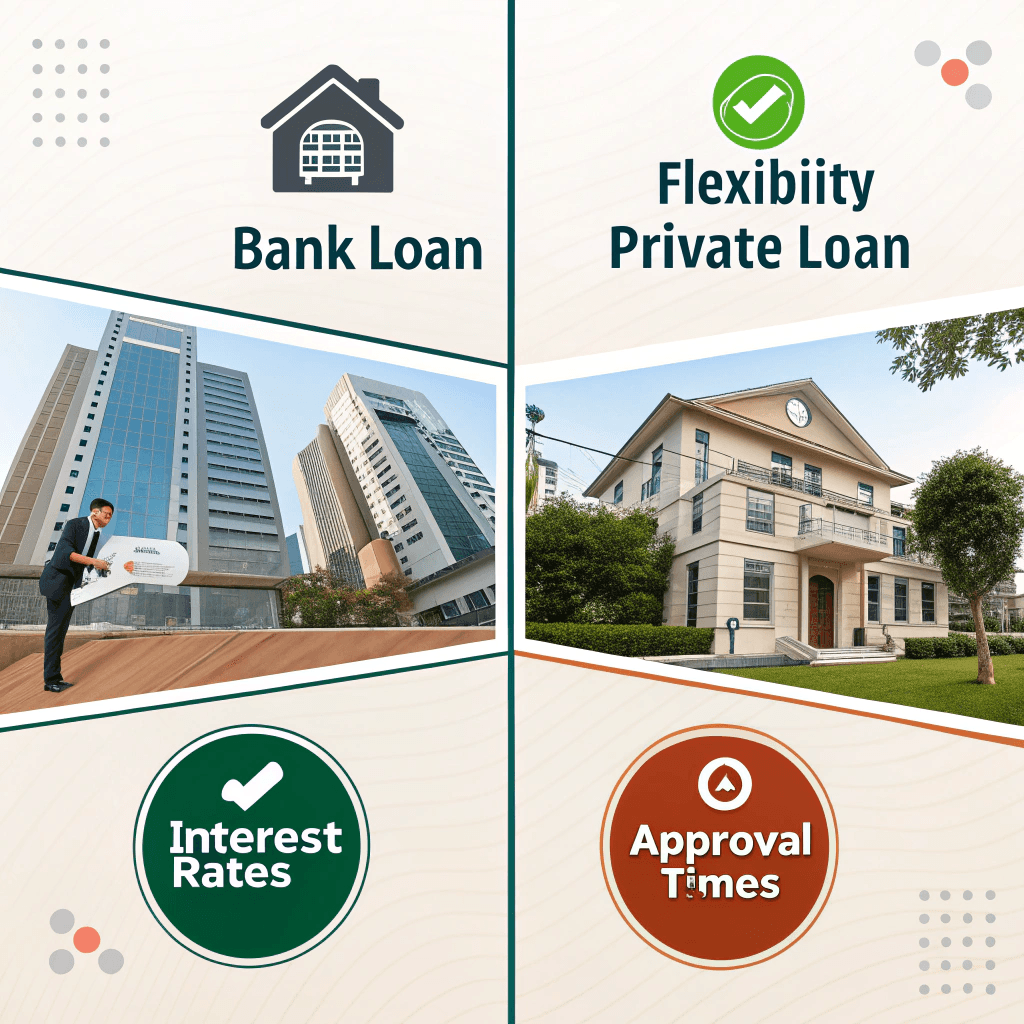
So what exactly is a private loan? It’s a form of financing offered not by a bank, but by a private investor or lending company. These lenders are often more flexible than banks and typically focus on the value of the property itself rather than your credit score or residency status.
The biggest benefit? Speed and simplicity. While banks may take months to approve a mortgage, a private lender can often approve your loan within a few days. Usually, the only thing they ask for is that the property you’re buying serves as collateral.
That means even if you’re a non-resident with no local income, you can still get financed—as long as the property is titled and legally clean.
But flexibility comes at a cost. Interest rates on private loans are generally 10% to 15% per year, sometimes even higher. Repayment terms are much shorter too, usually 3 to 5 years. That means these loans are better suited for short-term investments, quick flips, or buyers who plan to refinance with a bank later.
Is it risky? It can be. If you miss payments, private lenders can move quickly to initiate foreclosure through a local legal process called a “juicio hipotecario”, which allows them to seize and sell the property. That’s why it’s essential to read the contract carefully and always work with a real estate attorney.
If used correctly, a private loan can help you close a deal fast and secure a prime property. Just be realistic about the costs, have a solid repayment plan, and always get professional legal advice before signing anything.
What Lenders Expect: Guarantees, Interest Rates, and Common Pitfalls
Let’s get into the details: what exactly do lenders—whether banks or private—expect from you when you apply for a loan in Costa Rica?
The answer is almost always the same: the property itself must serve as collateral.
For bank mortgages, that property needs to be fully titled and registered at the Registro Nacional (Costa Rica’s national property registry). The bank will also require a professional appraisal, an insurance policy on the property, and possibly even a life insurance policy to secure the loan balance in case of death.
Private lenders are typically more flexible. Some might accept properties that are still in the process of titling or undeveloped land. But the flip side is, if you default on payments, they can take legal action quickly. Unlike in many countries, Costa Rican law allows lenders to foreclose relatively fast, especially under private contracts that waive some borrower protections.
So, what kind of interest rates are we talking about? As of late 2025, the averages look like this:
Local banks: 8% – 10%
International banks: 9% – 12%
Private lenders: 10% – 15%, sometimes more
Some loans are fixed-rate, but many are variable and tied to the Tasa Básica Pasiva, a benchmark rate published weekly by Costa Rica’s Central Bank.
Now, let’s talk hidden costs. Beyond the interest, you’ll also face fees for legal services, title registration, mortgage inscription, tax stamps, and more. These can easily add up to 3% to 5% of the property value, so plan your budget accordingly.
If you’re unsure where to begin, working with a real estate consultant or agency like Crespo Agency can save you a lot of trouble. They help connect you with reputable lenders, ensure your paperwork is in order, and guide you through the entire process.
In Costa Rica, who you work with really matters—and having someone on your side can make all the difference.
Transferring Funds from Abroad: Avoiding Blocks and Delays
Here’s something that catches many buyers off guard: transferring money into Costa Rica can be more complicated than you expect. And when you’re dealing with large amounts for a property purchase, it’s critical to get it right.
First, understand that Costa Rica has strict anti-money laundering laws. Any incoming transfer over $10,000 USD will be flagged by the receiving bank and subject to a compliance review. That means you’ll need to provide clear documentation of the funds’ origin—such as a contract from a property sale, inheritance documents, or bank statements showing consistent savings.
If you can’t provide the right documents, the bank can freeze or return your funds, causing serious delays in your purchase.
Second, banks in Costa Rica are not known for speed. Processing a wire transfer can take several business days, especially if it’s routed through intermediary banks. Add in public holidays, translation requirements, and old-school administrative processes, and things can drag out longer than expected.
Then there’s the matter of fees and exchange rates. Your sending bank may charge a fee, and the receiving Costa Rican bank might also take a percentage or apply a less favorable exchange rate.
One way to ease the process is by opening a local bank account. This allows you to move money internally once it’s in the country and helps you avoid some compliance hurdles. However, many banks will only let you open an account if you’re at least a temporary resident or actively involved in a real estate transaction with legal documentation.
Another increasingly popular option: online money transfer platforms like Wise, OFX, or local fiduciary services. These platforms often offer faster transfers, better transparency, and lower exchange rate margins.
Bottom line: never send a large transfer without consulting your real estate attorney first. Make sure all contracts are signed, the recipient account is verified, and all compliance paperwork is in order.
The money transfer step may not be glamorous, but it’s a critical piece of your real estate journey in Costa Rica—ignore it at your own risk.
Mistakes to Avoid and Practical Tips When Buying on Credit
By now, you can see that buying property on credit in Costa Rica is totally possible—but it’s not without its hurdles. Here’s a rundown of the biggest mistakes you should avoid, plus some practical tips to keep your purchase smooth and stress-free.
Mistake #1: Assuming it works like in your home country
Costa Rica has its own systems, timelines, and legal quirks. Don’t expect a mortgage approval in 48 hours or slick online banking tools. Be patient, and stay flexible.
Mistake #2: Skipping the title check
Before you even think about financing, make sure the property is legally clean. That means no hidden debts, no ownership disputes, and full registration with the Registro Nacional. Always hire a qualified real estate attorney.
Mistake #3: Underestimating closing costs
There’s more to pay than just the purchase price. Legal fees, notary services, taxes, wire transfer fees, insurance, and more can add up to 10% or more of the purchase price.
Mistake #4: Signing loan contracts you don’t fully understand
Especially with private loans, it’s essential to understand every clause. Some contracts have aggressive foreclosure terms or interest rate jumps after the first year.
Pro tip: Work with trustworthy professionals
This isn’t the time to go it alone. A good real estate agent, a sharp lawyer, and a seasoned agency like Crespo Agency can protect you from making costly mistakes. They know the local landscape, speak your language, and can act in your best interest.
Bonus tip: Always have a Plan B
What if the loan is delayed? What if your wire transfer gets blocked? What if rates rise? Always leave yourself some breathing room, a backup plan, and emergency funds.
Buying property in Costa Rica with financing isn’t a walk in the park, but with the right information and team on your side, it can absolutely be done. And once you’re relaxing in your new tropical home, you’ll be glad you did it right.
Conclusion
Buying property on credit in Costa Rica is absolutely doable—even as a foreigner—but it requires preparation, patience, and the right support. Whether you go with a traditional bank mortgage or explore private lending options, understanding the rules, risks, and timelines will make your journey a lot smoother.
If you’re a legal resident, banks may offer competitive terms, but expect a mountain of paperwork. If you’re not a resident, private lenders can provide fast access to capital, albeit at higher rates and shorter terms. Either way, you’ll need a solid understanding of local property law, and you should never sign anything without legal review.
Transferring funds into Costa Rica is another challenge that many overlook. But with good planning, trustworthy partners, and careful documentation, you can avoid costly delays.
The most important thing is to do your homework, work with professionals you trust, and never rush into a deal just because it sounds good. Costa Rica’s real estate market is full of opportunity, but it’s also different from what you may be used to.
With the right mindset and strategy, owning your slice of paradise is closer than you think. Financing your Costa Rican dream is not only possible—it’s entirely within reach.

Join The Discussion